 |
| CLICK HERE TO VIEW CURRENT ISSUE |
 |
| Best of NAMA 2026 |


|
 |
|
KANSAS CITY FED REPORTS LOAN PERFORMANCE STAYS STRONG AS FARM DEBT GROWS, DELINQUENCIES AT HISTORIC LOW
Dec. 4, 2023
by: Nate Kauffman and Ty Kreitman, Federal Reserve Bank of Kansas City
Farm debt balances at commercial banks grew steadily in the third quarter but loan performance remained strong. Despite some indications of slower lending activity in recent surveys and subdued loan demand for some lenders, outstanding debt at commercial banks in aggregate grew at a pace similar to the past year. Alongside ongoing strength in farm finances, delinquency rates on agricultural loans dropped for the third consecutive year and remained at historically low levels.
Steady loan growth has coincided with a pullback in deposit growth and firmed liquidity at agricultural banks. Higher interest rates have induced greater competition for deposits, pushed up costs of funding and compressed net interest margins slightly in recent months. Profits for agricultural banks, however, have stayed solid with support from higher interest income. Sound liquidity has continued to ease much of the risk surrounding elevated levels of unrealized losses at many banks and will remain important going forward.
Third Quarter Commercial Bank Call Report Data
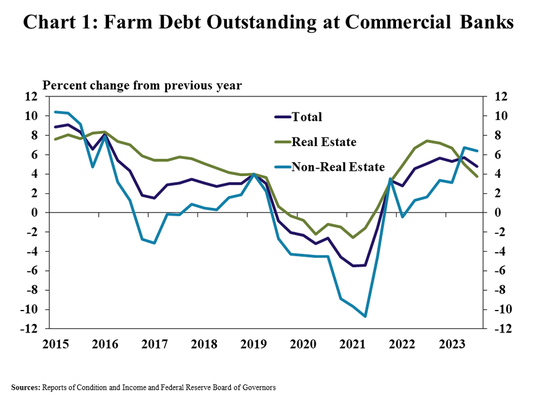
The balance of agricultural debt continued to increase alongside growing demand for production loans. According to commercial bank Call Reports, farm debt was about 5% higher than the same time a year ago and has increased at a similar pace for nearly two years (Chart 1). The pace of growth in non-real estate debt was steady while growth in farm real estate debt was softer than previous quarters.
Despite steady growth in total, farm debt remained subdued at some banks while growing considerably for others. Farm loan balances were lower than a year ago for a quarter of agricultural banks and half of non-agricultural banks (Chart 2). Outstanding debt grew by less than 10% for most agricultural banks, but increased more than 10% for a third of lenders.
To read the entire report click here.
|
|
|
|
|